Home Loans in Kyle and the Towns Around It
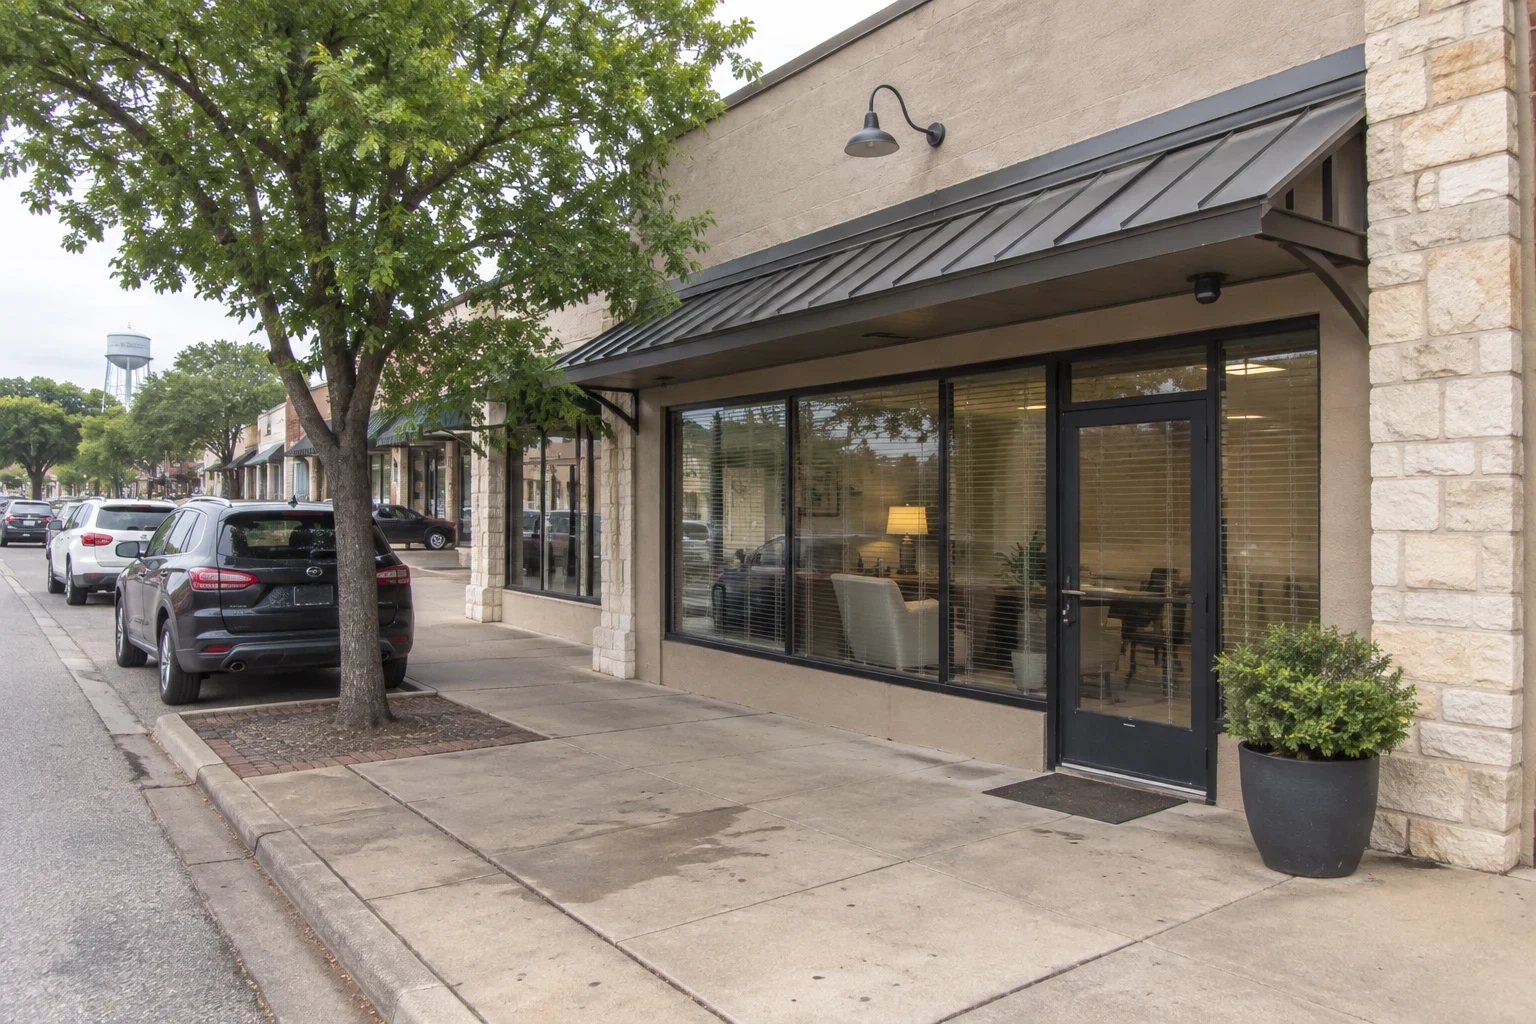
We help borrowers buy, refinance or tap equity in Kyle and the towns nearby. Meet us at our office or talk with us by phone and video. You work with a loan officer who builds taxes, HOA dues and insurance into your numbers from day one.
Towns we cover from Kyle
- Kyle
- San Marcos
- Buda
- Shady Hollow
- Redwood
- Wimberley
- Lockhart
- Belterra
Not on the list? Call (512) 881-3709 and ask.
Where We Work
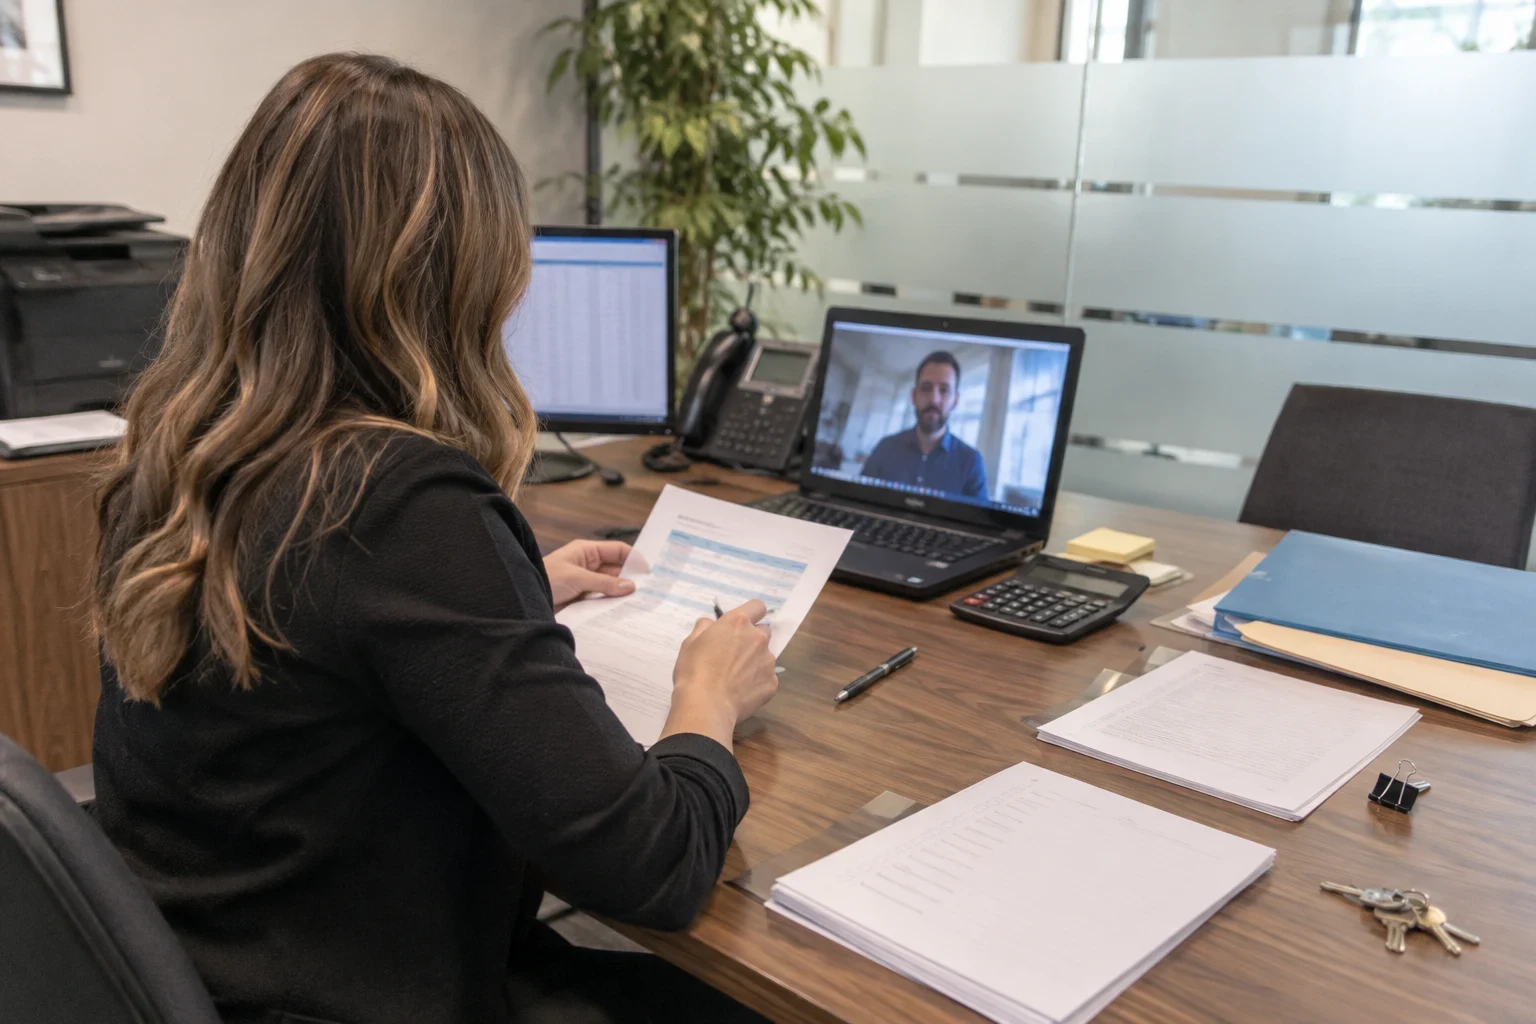
Most of our borrowers live in or are buying in Kyle, Buda and San Marcos. We also help buyers in Shady Hollow, Redwood, Belterra, Wimberley and Lockhart. Distance does not matter much in this line of work. Your file moves the same way whether you sit across our desk or talk with us on a video call from your kitchen table. Documents go back and forth, we explain each step, and you know what comes next.
Each town has its own mix. Newer subdivisions around Buda and Belterra often come with HOA dues. Wimberley leans toward larger lots, and some properties out there run on a well or septic system, which the appraiser and the lender will want to look at. Some addresses outside town limits may fit a USDA loan, but the lines are drawn property by property. We check the exact address before you count on it.
What Shapes a Home Loan Around Here
- 01
Property taxes and escrow
Texas has no state income tax, so local property taxes carry a big share of the monthly payment. Most loans collect taxes and insurance through escrow. We put those into your numbers at the start, so the payment you plan on is close to the one you see at closing.
- 02
HOA dues
Many newer neighborhoods across the area charge HOA dues. Lenders count them in your debt-to-income ratio. We ask about them early so they don't turn into a problem late in underwriting.
- 03
Weather and insurance
Central Texas gets hail, strong wind and heavy rain that can flood low ground. Insurance rates reflect that, and a property in a mapped flood zone may need flood insurance. We help you line up quotes before you lock a rate so the full payment is clear.
- 04
Housing age
Much of the area was built in the last twenty years, with older properties closer to the town centers. Older houses can raise appraisal or inspection questions. That matters most on FHA and VA loans, which have their own property standards.
- 05
Texas equity rules
Texas caps home equity borrowing at 80 percent of the value, counting what you already owe, and sets waiting periods before closing. That limits what a HELOC or cash-out refinance can give you. We run those numbers with you up front, before you spend money on an appraisal.
Get Your Numbers Before You Shop
Tell us where you're looking and what you have for a down payment. We'll give you rate quotes and a plain look at the monthly payment, taxes and dues included. If it makes sense, we can start your pre-qualification on the same call.