ServicesBank Statement Loans
Bank Statement Loans in Kyle, TX
If you work for yourself, your tax return may show a lot less income than you really earn. A bank statement loan lets us look at your actual deposits instead. We sit down with your statements, do the math with you and tell you plainly where you stand.
A home loan built around how you actually get paid
Self-employed borrowers write off trucks, tools, mileage and a home office. That is smart at tax time. It also shrinks the income a conventional lender is allowed to count. Plenty of contractors, realtors, salon owners and small business owners around Kyle earn steady money and still get turned down.
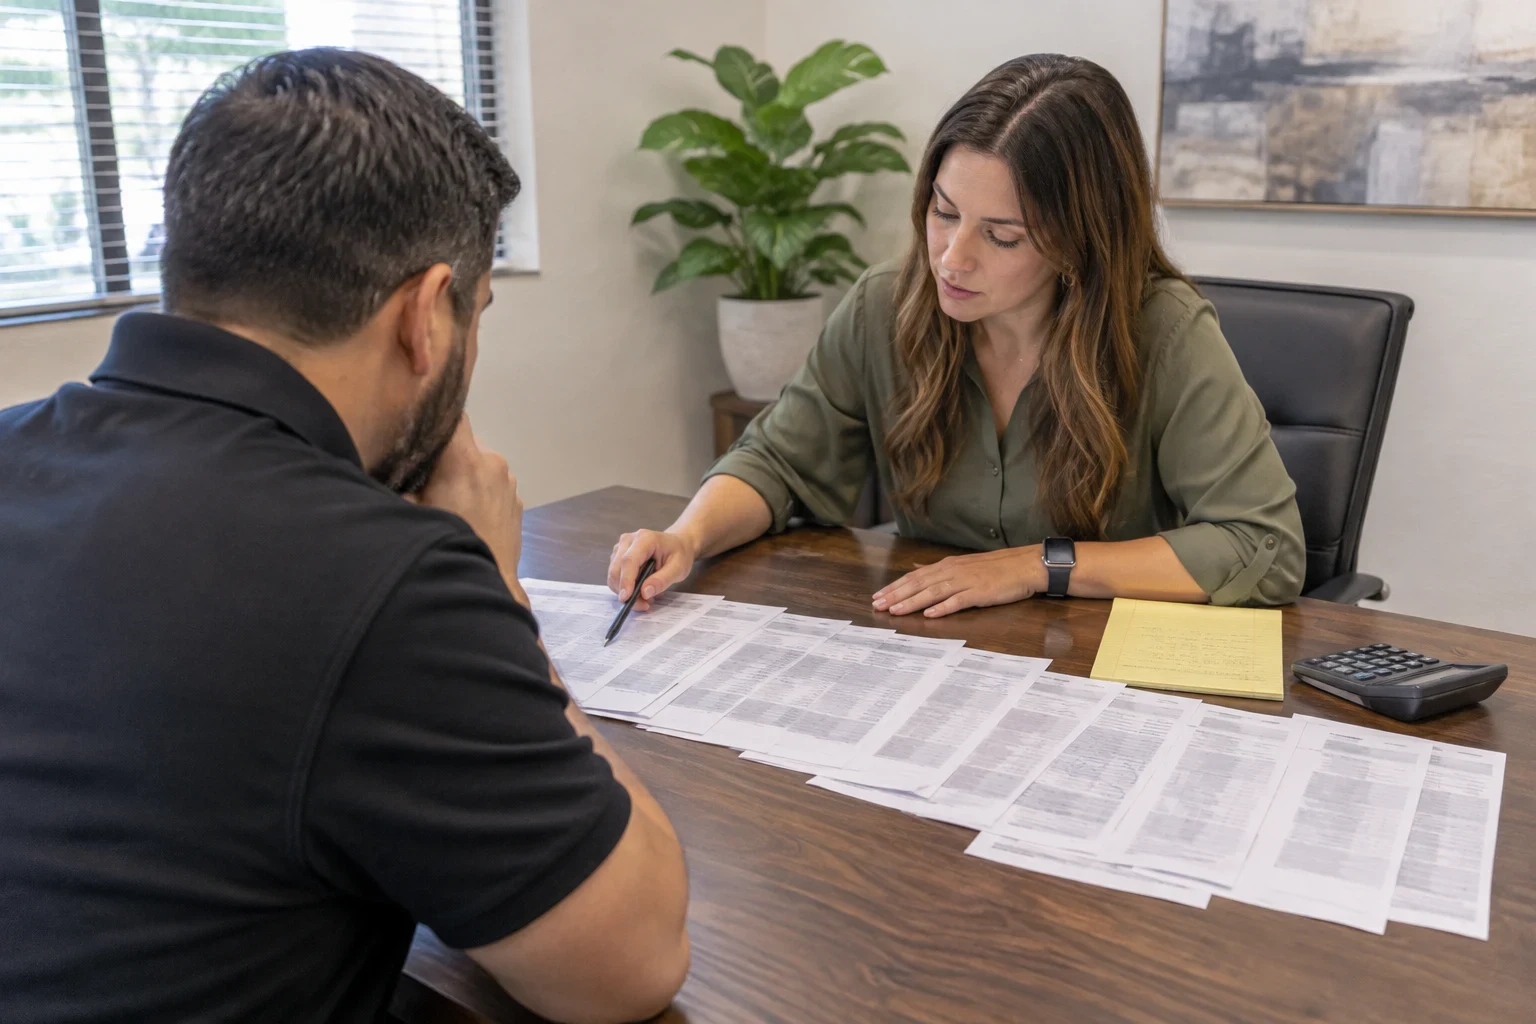
A bank statement loan uses 12 or 24 months of personal or business bank statements to figure your income. We add up the deposits, take out transfers and one-time money that is not income, and apply an expense factor to business accounts. What is left is the monthly income the loan is based on.
It is not the right fit for everyone. These loans usually carry a higher rate and a bigger down payment than a conventional loan. If your tax returns already show enough income, we will tell you so and point you toward Conventional Loans or FHA Loans instead.
What we handle on a bank statement loan
- Reading your statements line by line
- We go through every month and mark which deposits count as income. Transfers between your own accounts, loan proceeds and refunds come out. You see the same worksheet we use.
- Choosing 12 or 24 months
- A shorter window helps if business picked up recently. A longer one smooths out a slow season. We run both and show you which gives the stronger number.
- Personal versus business accounts
- Personal statements are usually counted at full deposits. Business statements get an expense factor, either a standard one or a figure your CPA or tax preparer confirms in writing. We explain which works better for your books.
- Comparing programs side by side
- Bank statement programs differ from one investor to the next. We compare them on rate, down payment and reserves, then walk you through the trade-offs by phone, by video or at our office.
- A pre-approval you can shop with
- Once the income is settled, we issue a pre-approval letter so your agent can write offers. Sellers want to know you can get to closing.
Signs a bank statement loan may fit you
Your tax return undersells you
Your deductions are legitimate, but the net income on paper is far below what lands in your account each month.
A lender already said no
You were told your income did not qualify, even though your bills are paid on time and your business is steady.
You are paid by 1099 or direct deposit
Realtors, consultants, drivers, tradespeople and gig workers often get paid in ways that W-2 rules do not fit well.
You own part of a business
K-1s and business returns can make income hard to document the usual way. Deposits are often simpler to show.
Your income grew fast
Two years of tax returns may still reflect the slow early days. Recent deposits can tell a truer story about what you earn now.
From first call to closing
- 1
A first conversation
You call and tell us what you do for work and what you want to buy or refinance. We ask about credit, savings and your rough down payment. No paperwork yet.
- 2
Gather your statements
You send 12 or 24 months of complete statements, every page. We also ask for something showing how long you have been self-employed, usually a business license or a CPA letter.
- 3
Income worksheet and options
We build the income worksheet and check it with you. Then we lay out rate, down payment and monthly payment for each program you qualify for.
- 4
Application, appraisal and underwriting
You complete the loan application, the appraisal is ordered and an underwriter reviews the file. Large deposits may need a short note about where they came from, so we flag those early.
- 5
Closing
We confirm the final numbers with you before closing day. Then you sign at the title company and get your keys.
What moves the rate on a bank statement loan
Bank statement loans are priced on risk, so two borrowers can get very different numbers. We cannot quote a rate until we see your credit and statements. These are the things that move it most.
- Credit score
- Higher scores get better pricing. A few late payments in the last year can push the rate up more than people expect.
- Down payment
- More money down lowers the lender's risk and usually the rate. Some programs require more down when the credit score is lower.
- Reserves
- Lenders want to see savings left after closing, counted in months of payments. More reserves can open better options.
- Property type and use
- A primary residence prices better than a second home or rental. Condos and multi-unit properties can carry their own adjustments.
- How clean the deposits are
- Frequent cash deposits, transfers between accounts or overdraft fees make income harder to verify and can limit your choices. Separate business and personal accounts help.
Bank statement loan questions
Something not covered here? (512) 881-3709
Do I still need to file taxes to get a bank statement loan?
You should be current on your taxes, but we do not use your returns to figure income. Some programs ask you to sign a form so the lender can confirm returns were filed. If you owe the IRS, tell us early so we can see whether a payment plan works with the program.
Can I use a bank statement loan to refinance?
Yes. Self-employed borrowers use them to refinance to a lower rate or to pull cash out of their equity. The same income math applies. If you only need access to equity and like your current rate, a HELOC may cost less, and we will compare both with you.
Why is the rate higher than a conventional loan?
These loans sit outside Fannie Mae and Freddie Mac guidelines, so the investors who buy them take on more risk. That shows up as a higher rate. Some borrowers use a bank statement loan to buy now, then refinance into a conventional loan once their tax returns show more income.
What if I mix personal and business money in one account?
It happens a lot, and it can still work. We may treat the account as a business account and apply an expense factor, or ask you to explain certain deposits. Going forward, a separate business account makes the next loan easier.
How long does it take to close?
It depends on how quickly your statements come in and how clean they are. Most of the time goes to the income review and the appraisal. We give you a realistic timeline after we see your file, not before.
Find out what your deposits qualify you for
Have your last few statements handy when you call. We will go over the numbers with you and tell you honestly whether this loan makes sense or another one fits better.